

ATM Cash Advance・Instant Money
by ATM.com, Inc.
4.5
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.5
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
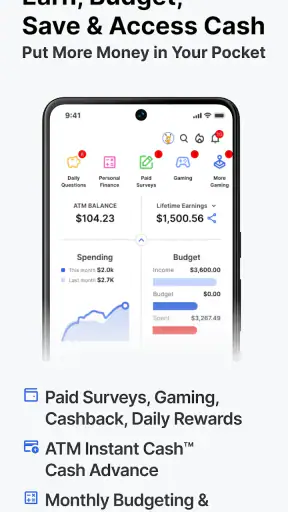
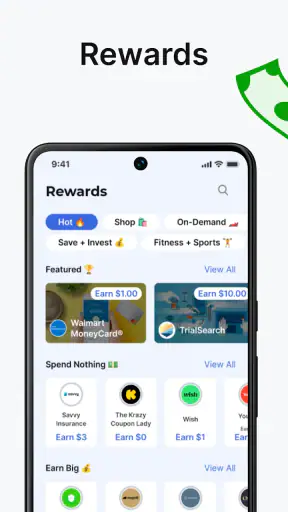
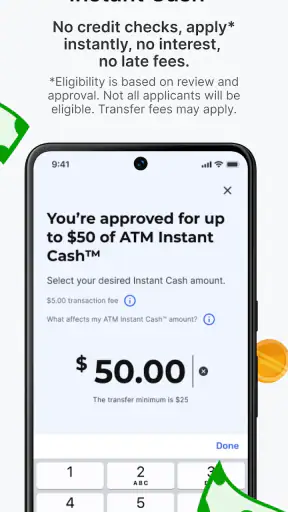
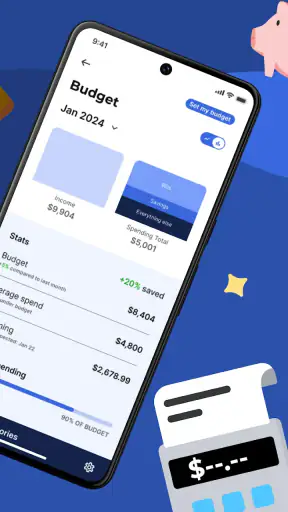
 Analysis by Getfullapps
I tried ATM Cash Advance・Instant Money as a practical finance app rather than treating it like a replacement for a bank account. That distinction matters. Its main appeal is the possibility of getting access to cash quickly while also finding ways to save, all from a phone. In my experience, the useful question is not simply whether the app can help in an urgent moment, but whether it fits the way you already manage money, especially if more than one person uses the same device.
The app is free to install and is published by ATM.com, Inc. It belongs to the finance category, carries an Everyone age rating, and has reached over a million installs. Its average rating is 4.5 from around 52 thousand ratings, with roughly 14 thousand written reviews. Those figures suggest that the concept is easy for many people to understand, but they do not remove the need to read the terms shown inside the app before accepting any cash advance.
How ATM Cash Advance fits into a shared household
A realistic use case is a household where one person handles regular bills while another needs occasional access to money between paydays. Imagine a phone kept in a shared living space: one partner checks an upcoming expense, another looks at a saving option, and a teenager may use the same device for unrelated apps. ATM Cash Advance can be useful in that environment only when each person treats the account as personal and keeps the app’s financial activity separate from casual shared phone use.
I would not think of it as a household wallet. The app is designed around an individual’s financial situation, so sharing a device does not mean sharing an account. A family member should not submit information, review an advance, or change account details on someone else’s behalf unless the account owner is directly involved and understands exactly what is happening. That simple boundary prevents a common mistake: assuming that a convenient shared screen is the same thing as shared financial authority.
The app’s cash-advance angle is its most immediate attraction. It presents access to instant cash advances without a credit check, but that wording should not be interpreted as free money or guaranteed approval for every user. Before accepting anything, I would look carefully at the repayment timing, any applicable costs, and the effect on the next available paycheck or balance. A quick solution can become uncomfortable if it merely moves the same shortage a few days forward.
The best way to use ATM Cash Advance is as a short-term planning tool, not as a permanent bridge between paychecks. I found that mindset more useful than opening the app whenever an unexpected purchase appears. If the expense is predictable, saving toward it is usually healthier. If it is urgent and unavoidable, the advance feature may deserve consideration, but only after checking whether repayment will leave enough for rent, food, transport, and other essentials.
Keeping setup personal on a shared phone
During setup, I would create the account for the actual user, not for the household as a whole. That means using the correct personal details and reviewing every screen rather than handing the phone to another family member to finish. Finance apps are not the place for guesswork. A wrong entry can create confusion later, particularly when the app needs to match a person’s financial information or present an offer based on that person’s circumstances.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
There is also a practical device issue. If several people unlock the same phone, the account owner should avoid leaving the app open on a page that displays sensitive financial information. I would close the app after checking an advance or savings activity and avoid discussing private figures aloud in front of children or visitors. These are ordinary habits, but they matter more here than they do with a weather or entertainment app.
ATM Cash Advance runs on Android from version 8.0 onward, which makes it accessible on many older phones as well as newer devices. Its current version is 2.135.0. That broad compatibility is helpful for households that share an older spare phone, although I would still keep the operating system updated when possible and use the device’s normal screen-lock protection.
One useful setup habit is to decide in advance who is allowed to use the phone for financial tasks. If one partner owns the account, the other can help compare a bill or talk through a decision without taking over the account itself. This sounds overly cautious until an accidental tap, a misunderstood screen, or an unplanned advance creates a real problem. Clear roles are easier than trying to reconstruct what happened afterward.
Coordinating money without confusing account ownership
The app can support a conversation between adults, but it does not replace a shared household budget. I would use it alongside a simple note or spreadsheet that records who is responsible for an expense, when money is expected, and whether a cash advance would affect a joint bill. The purpose is coordination, not duplication. The account remains personal, while the household discussion deals with the consequences.
For example, if one person considers using an advance to cover a utility bill, I would first compare that option with the household’s available cash and the date of the next income. Then I would tell the other adult exactly what the repayment means for the shared budget. This prevents the common situation where one person sees immediate relief while the other discovers later that grocery money has effectively been committed.
The saving side of the app may be more valuable for this kind of coordination than the emergency feature. A household can use the app as a prompt to separate everyday spending from money intended for a future need, while still keeping each person’s account activity distinct. I would not assume that a saving feature automatically creates a joint goal or allows another person to monitor progress. Instead, both adults should agree on the goal outside the app and discuss updates openly.
A small but important workflow is to review the app at a calm time, not while standing at a checkout or dealing with a late bill. That gives you room to understand the available choices and consider the next few days. In my experience, the app is easier to judge when it is part of a planned money check-in rather than a panic button.
Age, trust, and responsible use
The Everyone rating describes the app’s store age classification, but it should not be treated as permission for a child to manage advances or financial decisions. A young person may see the app on a shared device, yet cash access involves adult judgment, personal information, and repayment responsibility. I would keep the account with the adult who understands the household’s income and obligations.
That does not mean children must be excluded from every money conversation. An adult could explain the difference between saving and borrowing, show how an unexpected expense affects a budget, and discuss why an advance needs to be repaid. The important line is between education and access. A child can learn from the conversation without being given control of the account or the phone during a transaction.
Trust also matters between adults. If a partner is helping with setup, I would remain present, read the screens together, and make sure both people agree about what information is being entered. If the phone belongs to someone else, I would not save personal details in a way that makes future access effortless for another user. Financial convenience should never depend on everyone in the home having the same level of access.
People who are uncomfortable sharing financial information with a partner may prefer to keep their use entirely private and manage household contributions separately. That can be reasonable, but it requires honest planning around shared expenses. ATM Cash Advance cannot solve a communication problem. It may provide an individual tool, but the household still needs an agreement about bills, repayment, and emergency spending.
Where it beats familiar alternatives, and where it does not
Compared with asking a friend or family member for a short-term loan, the app offers a more direct, phone-based process and avoids turning a personal cash shortage into an awkward conversation. Compared with a traditional bank overdraft, its no-credit-check cash-advance positioning may appeal to someone who wants to explore an alternative route. Compared with a credit card, it may feel more focused on a specific short-term need rather than encouraging open-ended spending.
Those comparisons have limits. A bank account remains better for regular deposits, bill payments, account history, and broader money management. A credit card can be more suitable for a planned purchase when its terms are understood and the balance can be cleared reliably. A household savings buffer is better than either option for a predictable emergency. The app is most relevant when the need is temporary and the user has a realistic way to cover the repayment.
I would also avoid comparing an advance with a normal savings transfer as though they were interchangeable. Saving reduces future pressure; borrowing increases the need for future cash. The app’s ability to present both ideas in one finance experience is convenient, but the financial direction is completely different. If you can wait, saving is usually the cleaner choice. If you cannot wait, examine the full cost and timing before proceeding.
One non-obvious trade-off is that convenience can make a decision feel smaller than it is. A few taps on a familiar phone may seem less serious than visiting a bank or speaking to another person, even though the repayment still affects the same household budget. I recommend writing down the amount you need, the date you expect to repay it, and the bills that come before that date. If the plan does not work on paper, the app will not make it work in practice.
Everyday friction worth considering
The app’s promise is strongest when speed matters, but speed also leaves less room for reflection. I would read each offer carefully, especially if the available amount or repayment arrangement differs from what I expected. “Instant” describes the intended convenience of access; it should not be treated as a guarantee that every user will receive the same result or that money will solve the underlying problem.
Another limitation is emotional rather than technical. Someone already under financial pressure may open the app repeatedly, hoping that another advance will cover the previous one. That pattern is a warning sign. If you need the feature for several pay cycles in a row, I would step back and look for a broader solution: reducing a recurring expense, contacting a bill provider, increasing income, or speaking with a qualified financial counselor.
I also found that a finance app needs more deliberate checking than an ordinary utility. Keep records of what you accepted, when repayment is expected, and how the transaction fits with other accounts. Do not rely on memory simply because the app is on your phone. A household calendar or written budget can make the timing visible to the people affected without giving them access to private account screens.
For someone who only wants a basic spending account, ATM Cash Advance may feel too focused on short-term cash access. For someone with stable savings and no need for advances, a bank’s budgeting tools may be more familiar and comprehensive. The app makes more sense for a user who wants a free finance app with saving options and a possible emergency-cash route, while remaining willing to examine the conditions personally.
Who should consider it and who should skip it
I would recommend trying ATM Cash Advance to an adult who occasionally faces a timing gap, wants to explore saving habits, and can make repayment decisions without pressure from another person. It may also suit a household where one adult manages a personal account while both adults communicate clearly about any effect on shared bills.
I would be cautious if your income is already committed before the next payday, if you are looking for a long-term debt solution, or if you expect the app to replace a full bank account. I would also skip it for a child’s personal use, for an account that several people intend to operate together, or for any situation where the repayment details are not completely clear.
Before installing, decide what job you want the app to perform. If the answer is “help me build a small buffer,” focus on the saving side and review progress periodically. If the answer is “get me through one unavoidable expense,” calculate the repayment first. If the answer is “keep my whole household’s finances in one place,” this is probably not the right tool by itself.
My household verdict
After using it with a shared-device mindset, I see ATM Cash Advance・Instant Money as a focused finance app rather than a complete household money center. Its free access, approachable design, saving angle, and cash-advance option give it a clear place for adults managing occasional shortfalls. The developer, ATM.com, Inc., has built something that can be useful when the user understands the difference between convenience and affordability.
My final advice is to keep the account personal, discuss household consequences openly, and treat every advance as a decision that deserves a written repayment plan. The app is not the best choice for children, joint account management, or ongoing financial strain. For the right adult user, though, it can be a practical addition to a broader budget, especially when used sparingly and with attention to the terms shown at the moment of use.
In short, I would recommend it as a carefully managed backup, not as money to depend on. If that boundary suits your situation, ATM Cash Advance・Instant Money is worth considering. If your household needs shared visibility, long-term planning, or a stable place for everyday banking, choose a tool built for those jobs and let this app remain a limited, personal part of the plan.
Pros
- Fast approval process for cash advances.
- User-friendly interface and navigation.
- No hidden fees or charges involved.
- Supports multiple financial institutions.
- Strong data encryption for security.
Cons
- High interest rates on cash advances.
- Limited customer support availability.
- Requires access to sensitive personal data.
- Not available in all regions or countries.
- Potential impact on credit score.
FAQs for ATM Cash Advance・Instant Money
What is ATM Cash Advance・Instant Money?
ATM Cash Advance・Instant Money is a financial app designed to provide users with quick access to cash advances directly from their smartphones. It allows users to request instant money transfers to their bank accounts, offering a convenient solution for unexpected expenses or emergencies.
How does the cash advance process work?
The process is straightforward. Once you download and install the app, you need to sign up and verify your identity. After linking your bank account, you can request a cash advance. The app assesses your eligibility based on your financial history and transfers the approved amount to your account.
Is the ATM Cash Advance app secure?
Yes, the app employs industry-standard security measures to protect your personal and financial information. This includes encryption protocols, secure login procedures, and continuous monitoring for fraudulent activities. Ensure you download the app from official app stores to avoid security risks.
Are there any fees associated with using ATM Cash Advance?
While the app provides a convenient service, there may be fees associated with cash advances. These can include service fees, interest rates, or transaction charges. It is essential to review the terms and conditions within the app to understand the cost structure before proceeding with any transactions.
What are the requirements to use the app?
To use ATM Cash Advance・Instant Money, you must be at least 18 years old, have a valid bank account, and reside in a region where the app is supported. Additionally, a stable internet connection and a compatible Android or iOS device are necessary for app installation and operation.

ATM Cash Advance・Instant Money
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@atm.com, visit https://atm.com, or review their https://atm.com/privacy-policy.










